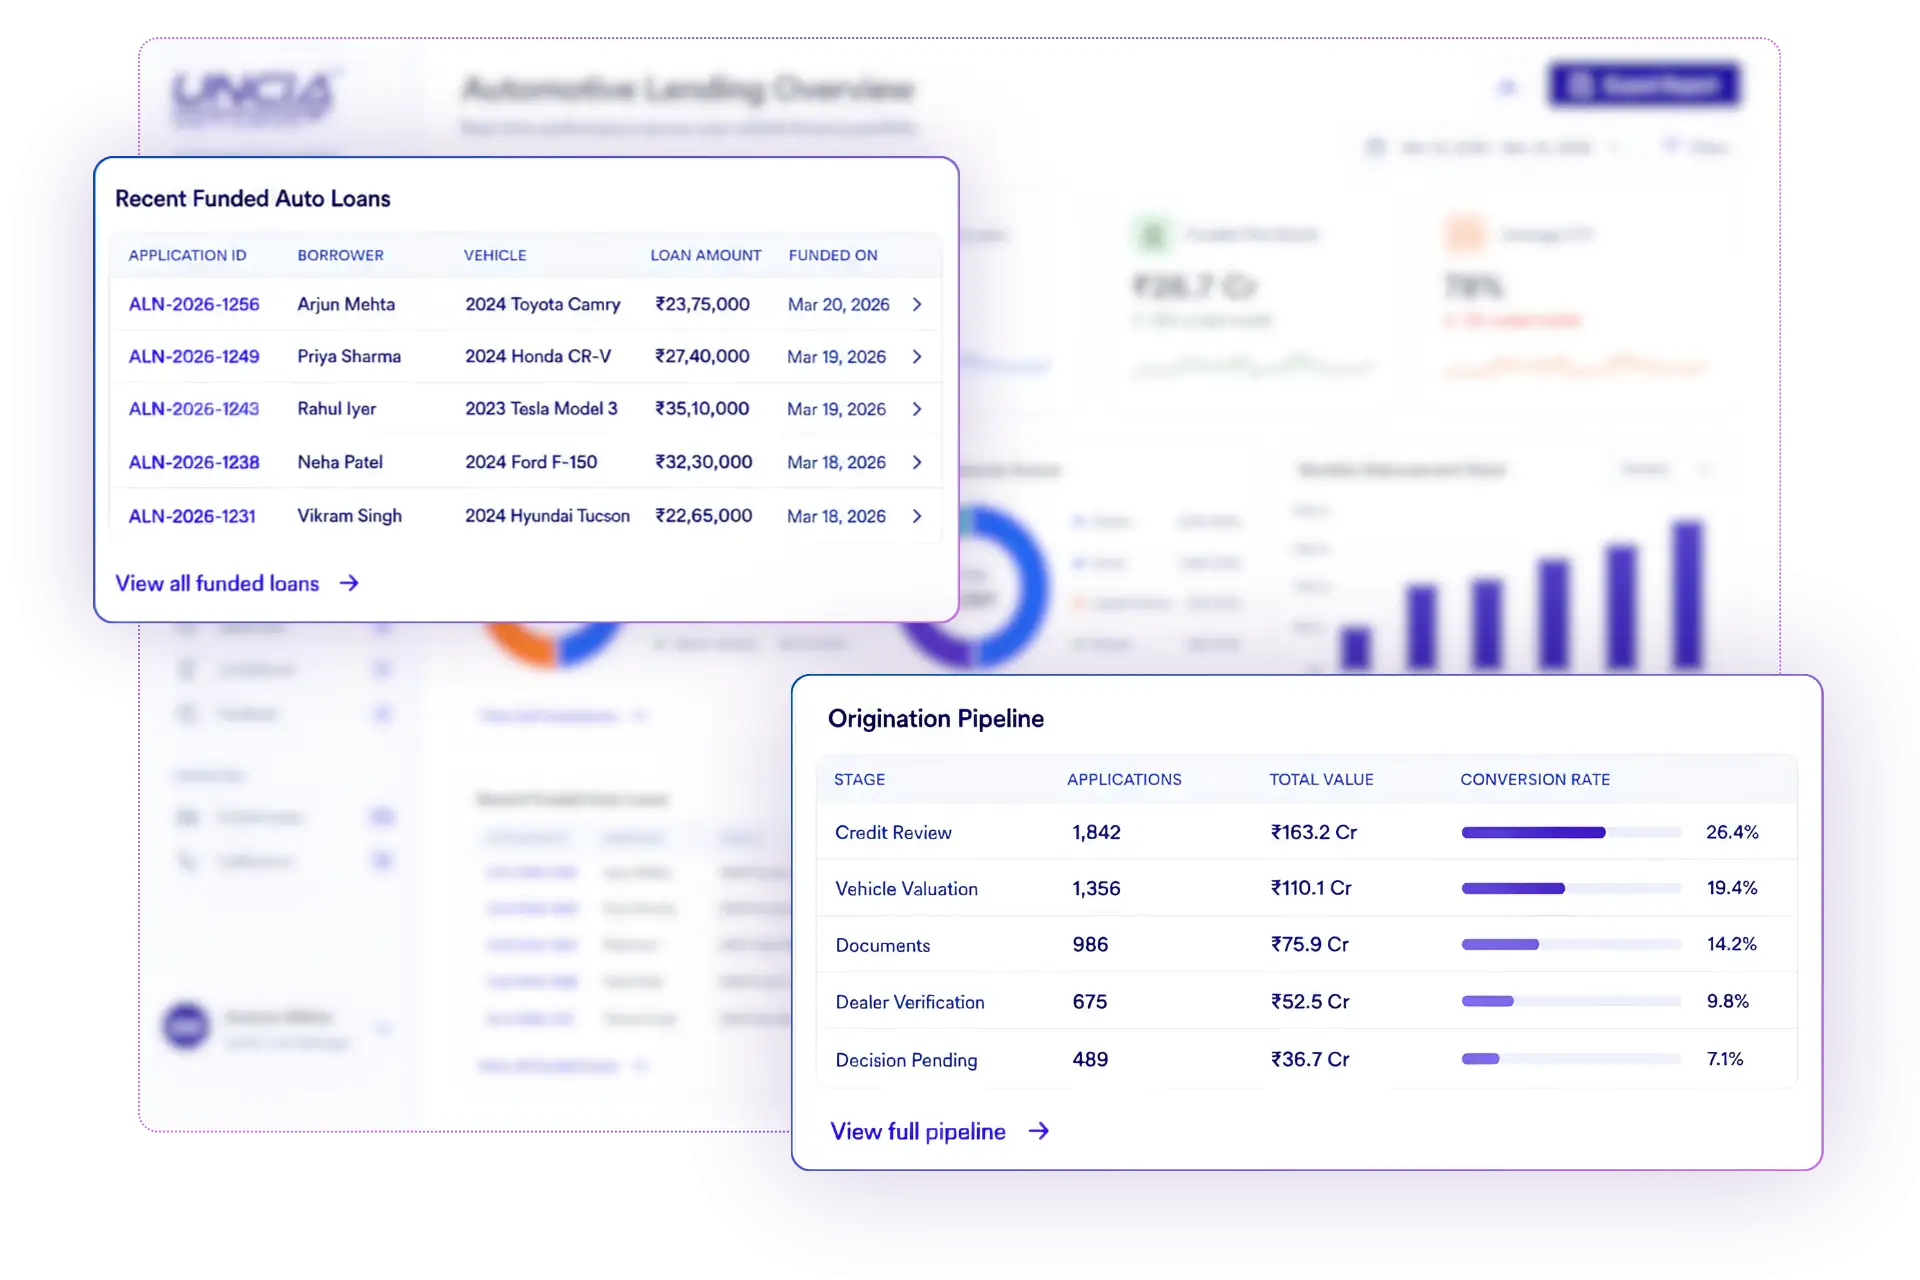
Automotive Lending Platform
The wheels business runs on speed.
Your lending platform should too.
UnciaPrime for origination. UnciaLeap for servicing.
Built for the specific demands of auto finance.
Auto finance is not a simple loan product.
Most LOS and LMS platforms were not built for it.
Vehicle loans move fast, or they should.
Dealers expect turnovers in hours, not days. But most origination platforms create friction at exactly the moments that cost you the deal.
- Dealer portals that are clunky, slow, and require constant back-and-forth to submit and track applications
- Manual valuation and RC verification steps that hold up decisioning long after the borrower is ready to sign
- Credit rule changes - For a new vehicle segment, a new OEM tie-up, or a revised LTV policy that require IT tickets and take weeks to reflect in the system
- Multiple product variants (two-wheeler, three-wheeler, commercial vehicle, used car, EV) each requiring different workflows but sitting on the same inflexible platform
- Bureau pulls, income verification, and KYC running in sequence rather than parallel, stretching TAT unnecessarily
- No real-time visibility into where an application is stuck and why
Once the keys are handed over, the complexity does not end.
It just moves.
- EMI collection across multiple channels with no consolidated view of payment status
- Repossession and auction workflows managed through spreadsheets and manual tracking
- Part-payment, foreclosure, and hypothecation removal requiring operations teams to intervene at every step
- Collections prioritisation done by gut feel because the platform does not surface early delinquency signals
- RC transfer and NOC issuance processes that are entirely manual and delay the borrower's experience after full repayment
- Regulatory reporting on vehicle finance portfolios that takes days to compile because the data sits in multiple places
Two products. One platform.
Two products.
One platform.
Built for every stage of the vehicle loan lifecycle.
Loan Origination
For the dealer floor and the credit desk, simultaneously.
UnciaPrime is built around one principle: the credit team owns the platform. Your business heads configure loan products, set LTV parameters, define bureau logic, and launch new OEM or dealer programmes without raising a single IT ticket.
What changes for your origination team:
- Dealer portal that field teams can use on a phone - application submission, document upload, and status tracking without a desktop or a branch visit
- Parallel processing of bureau, valuation, income verification, and KYC from the moment the application is submitted and not in sequence
- Credit rule changes - new vehicle segment, revised eligibility for EVs, updated LTV for used cars: live the same day your team decides to make them
- Product variants for two-wheelers, three-wheelers, CVs, used cars, and EVs each with their own workflow logic, configured by your product team
- Dealer and DSA management built in - onboarding, payout tracking, and performance visibility in one place
- RC verification and valuation integrations through Uncia Connect: pre-built, not custom-built
Loan Management & Servicing
For the collections floor, the operations desk, and the borrower on day 731.
UnciaLeap handles every stage of a vehicle loan after disbursement, not just the clean repayments but the edge cases that define your portfolio quality and your borrower experience.
What changes for your servicing team:
- EMI collection consolidated across NACH, UPI, cash, and digital channels with real-time reconciliation
- Early delinquency signals surfaced by the platform 30 to 45 days before the first missed payment, so your collections team calls before the borrower defaults, not after
- Repossession workflow managed inside the platform: field visits, repo status, auction initiation, and recovery tracking in one place
- Foreclosure, part-payment, and hypothecation removal processed by your team without manual intervention or vendor involvement
- NOC generation automated and triggered immediately on full repayment. The borrower gets it in minutes, not days.
- RTO integration for RC transfer tracking. No manual follow-up by operations.
- Regulatory reporting on your vehicle finance portfolio available on demand, not after a week of data assembly
The AI that matters in auto finance is not in a pitch deck.
It is in the workflow.
Auto finance generates more touchpoints per loan than almost any other retail product: dealer interaction, valuation, registration, insurance, collection, repossession, RC transfer, NOC. At each of these points, there is a version of the work that requires a person and a version that does not.
Uncia’s AI capabilities, developed in collaboration with IIT Madras, are built into the workflow at the moments where they change outcomes – not layered on top as a feature.

Onboarding Acceleration
Document processing for vehicle loans - Aadhaar, PAN, income proof, RC copy, insurance etc. handled in 3 to 5 seconds per document with 90 to 95 percent extraction accuracy. Cross-referencing across documents flags mismatches before they reach a credit officer. What used to take your operations team 2 to 3 days now happens before the dealer finishes the test drive conversation.

Credit Decisioning
Applications where the data tells a clear story are routed to automated approval. Applications that genuinely need credit officer judgment are flagged and prioritised. Your credit team spends their time on the 20 percent of applications where their judgment changes the outcome (not on the 80 percent where the data already has the answer)

Collections Intelligence
Payment behaviour patterns in your vehicle finance portfolio tell you who is at risk 30 to 45 days before the first EMI is missed. UnciaLeap surfaces these signals so your collections team can make a retention call when it is likely to work (not a recovery call when it is not)

Dealer Experience
Status updates, document deficiency alerts, and sanction notifications pushed in real time to the dealer portal mean less calling, less chasing, and faster funding decisions at the dealership floor.
Trusted by lenders who move as fast as their borrowers do.
Over $25 billion in AUM managed on Uncia across our deployments.
Including some of India's most active vehicle finance portfolios.
Common questions
Frequestly Asked Questions
We already have an LOS for vehicle loans. Why would we switch?
The question worth asking is not whether your current platform works. It is what it costs to make it work: in IT bandwidth, in change request backlogs, in TAT that loses you dealer relationships, and in manual processes your operations team runs because the platform does not cover them. We are happy to do a one-hour workflow diagnostic before any product conversation.
Does UnciaPrime support multiple vehicle categories - two-wheelers, CVs, EVs, used cars etc. on the same platform?
Yes. Each product category has its own configurable workflow, credit logic, and documentation requirements. Your product team configures these independently. Launching a new EV financing variant does not require a new implementation.
How long does implementation take for a vehicle finance lender?
Our fastest deployment took 97 days from contract to full production. For a vehicle finance lender with defined product variants and an existing dealer network, implementation time is driven by your team’s configuration pace, not by ours.
We have a large dealer network. How does UnciaPrime handle dealer onboarding and management?
Dealer onboarding, payout configuration, login creation, and performance tracking are all managed within UnciaPrime. Dealers access a mobile-ready portal for application submission and status tracking. DSA management is handled in the same system.
What integrations are available for vehicle finance: valuation, RTO, bureau?
Uncia Connect includes pre-built integrations for major credit bureaus, vehicle valuation platforms, RC and insurance verification, and Aadhaar and PAN-based KYC. These are activated, not custom-built. Your team configures which providers to use.
Is there a separate cost for UnciaLeap versus UnciaPrime?
We price on a pay-as-you-grow model based on origination volume. The commercial model is designed to scale with your portfolio, not ahead of it. We will share a detailed pricing overview once we understand your portfolio size and product mix.
How does the collections intelligence work for vehicle loans specifically?
UnciaLeap monitors payment behaviour patterns across your vehicle finance portfolio and flags accounts showing early stress signals: typically 30 to 45 days before the first EMI is missed. Your collections team receives a prioritised list each morning rather than reacting to defaults after they occur. Repossession workflow, when required, is also managed inside the platform.
Get Started
See it in your lending context - not a generic demo.
Tell us which product you are looking at and what your institution does. We will prepare a session that speaks directly to your workflow - your loan products, your compliance requirements, your team's situation. 30 minutes.
No commitment. No sales pressure. Just a direct conversation about whether this is the right fit.
- info@uncia.ai
- www.uncia.ai